
The Story:
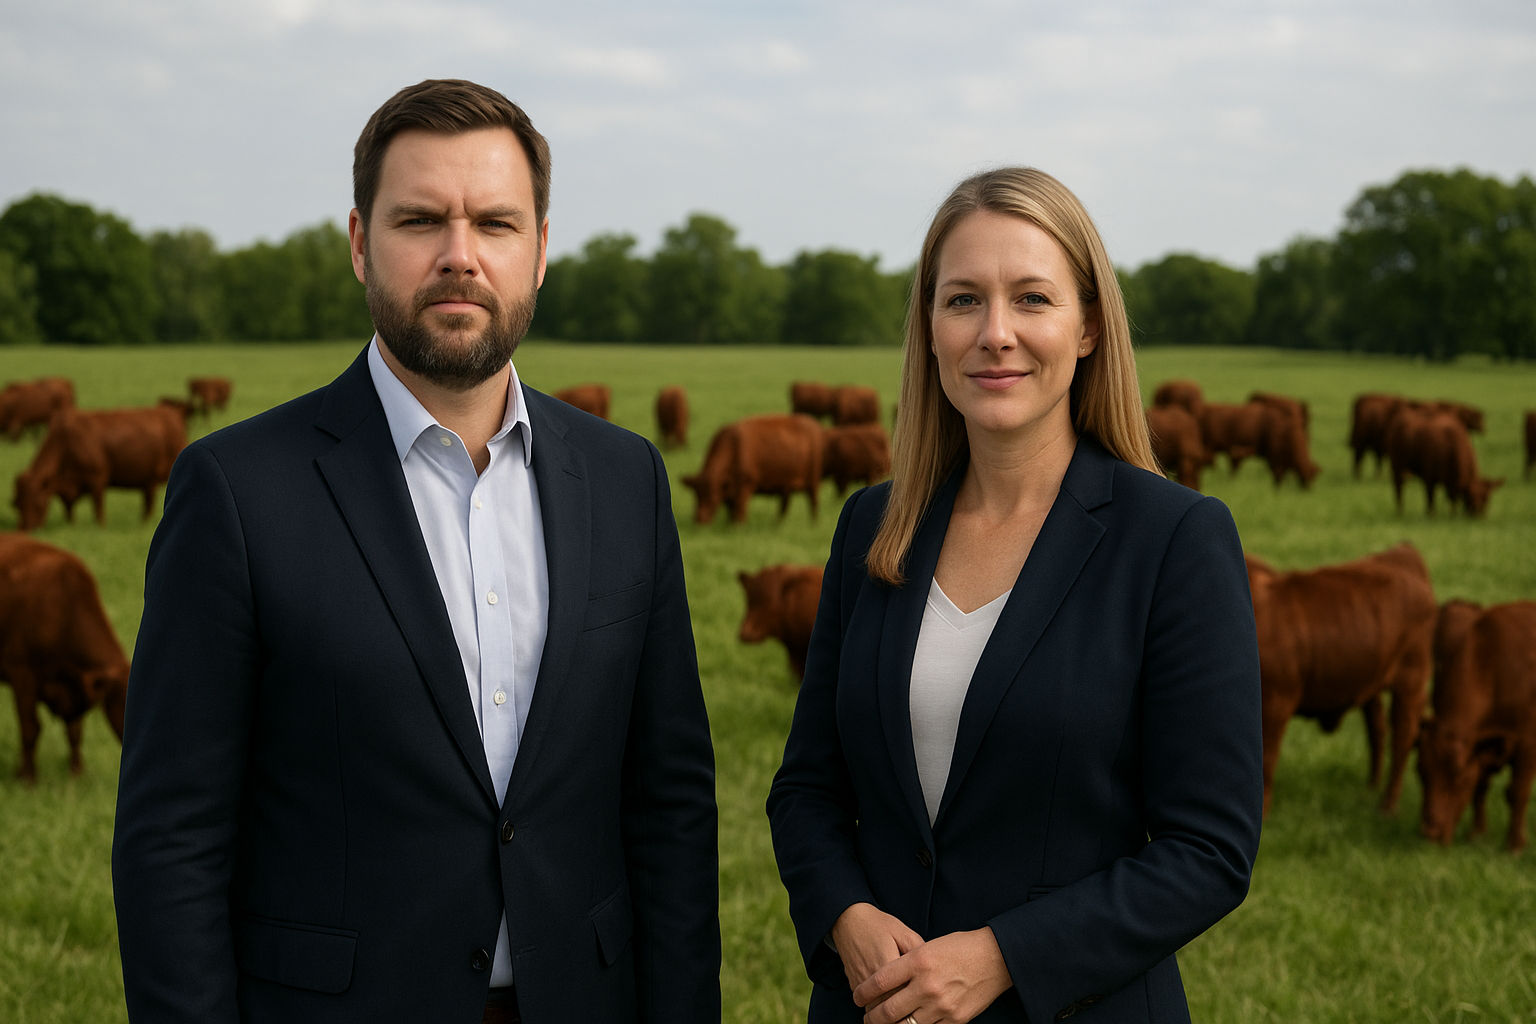
In a major federal policy action aimed at reshaping North American livestock and meat supply chains, Vice President J.D. Vance and U.S. Agriculture Secretary Brooke L. Rollins announced that independent meat and poultry processors across 40 states are slated to receive $57,424,130 in competitive federal funding through the Meat and Poultry Processing Expansion Program (MPPEP). Managed by USDA Rural Development's Rural Business-Cooperative Service, this latest capital allocation encompasses 147 tentative grant awards designed to provide direct financial backing to small- and medium-sized processing enterprises. The overarching strategic mission of the initiative is to expand domestic slaughter and fabrication capacity, introduce robust market competition against multinational meatpacking conglomerates, and build enduring supply chain resiliency. By financing physical facility modernizations, high-throughput automated processing equipment, expanded blast-freezing systems, cold-chain storage capacity, and USDA Food Safety and Inspection Service (FSIS) compliance upgrades, the federal investment seeks to break the chronic processing bottlenecks that have historically constrained independent livestock producers, commercial feedlots, and integrated regional growers.
The federal funding surge arrives at an exceptionally critical juncture for the domestic cattle, swine, and poultry sectors, which have long wrestled with extreme consolidation across the meatpacking complex. Four dominant packers currently control upwards of 85 percent of U.S. steer and heifer slaughter and more than 67 percent of commercial pork processing, leaving independent livestock feeders acutely vulnerable to capacity constraints, formula-pricing distortions, and extended delivery queues. This structural vulnerability has been exacerbated by the multi-year contraction of the domestic beef cow herd, which remains anchored near 75-year historical lows. As evidenced in the USDA's latest monthly Cattle on Feed data, September feedlot placements plunged 12 percent year-over-year to 1.78 million head—establishing the lowest September placement figure since modern statistical records began in 1996. When commercial packing conglomerates periodically slow chain speeds, curtail operating shifts, or undergo maintenance downtime, finished cattle and hogs rapidly accumulate in feedlots and finishing barns. This captive dynamic forces producers to maintain market-ready animals on costly rations past optimal harvest windows, inflating feeding expenses, deteriorating carcass yield grades, and eroding producer operating margins.
Crucially, the 147 awarded projects target acute 'shackle space' deficits across foundational livestock feeding corridors, spanning key production states including Iowa, Texas, Nebraska, Kansas, Missouri, Minnesota, Georgia, North Carolina, and Pennsylvania. Under the MPPEP framework, recipient processors will significantly expand daily kill-floor throughput, add value-added further-processing and portioning infrastructure, and install advanced packaging automation. For independent cattle ranchers, commercial swine producers, and regional poultry growers, these decentralized facilities create viable, localized harvest alternatives that diminish dependence on long-haul transit to remote corporate packing hubs. By shortening transportation corridors, producers can substantially mitigate transit shrink, reduce freight and diesel fuel expenditures, eliminate multi-week slaughter booking delays, and negotiate transparent cash-market bids that accurately reflect the true market value of their finished livestock.
Why It Matters:
For animal feed manufacturers, commercial feedlot managers, swine nutritionists, and integrated poultry operators, the expansion of independent processing capacity carries profound implications for herd management economics and ration cost control. In commercial feeding enterprises, feed inputs represent between 65 and 70 percent of total live production costs, making animal turnover velocity a vital determinant of operational solvency. When slaughter bottlenecks force finished animals to linger in feedlots or finishing barns beyond their target slaughter dates, feed conversion ratios (FCR) deteriorate rapidly. In beef feedlots, cattle held 10 to 20 days past optimal finish hit a steep point of diminishing marginal returns, where average daily gain (ADG) falls precipitously while daily consumption of expensive starch and protein rations continues unabated, adding $25 to $40 per head in unrecoverable feed costs. In commercial swine barns, delayed marketings lead to severe pen overcrowding, heightened mortality risks, and heavy packer carcass-weight discounts on over-finished hogs. By unlocking consistent regional shackle space, the MPPEP expansion ensures animals exit feeding pens on schedule, allowing nutritionists to formulate finishing rations for peak biological efficiency rather than costly holding diets.
Beyond individual herd metrics, dispersing 147 modernized processing facilities across 40 states fundamentally reshapes regional feed manufacturing logistics and grain merchandising demand. The traditional concentration of mega-scale packing plants in a handful of Midwest and High Plains centers concentrated grain and protein meal consumption into rigid, geographically isolated feeding enclaves. In contrast, a decentralized network of thriving independent processors fosters regional livestock feeding clusters, creating robust local demand for commercial feed mills, independent grain elevators, and custom compounding facilities. Local feed mills gain steady, predictable off-take for complete feeds, ground corn, distillers dried grains with solubles (DDGS), and soybean meal, while nutritionists can tailor specialty rations—such as non-GMO, antibiotic-free, or locally sourced identity-preserved feeds—commanding higher mill margins. Furthermore, expanded regional slaughter operations generate an expanded local supply of rendered animal proteins, including ruminant meat and bone meal (MBM), poultry by-product meal, and feeding fats, establishing circular local nutrient flows that lower feed ingredient procurement costs across rural communities.
What to Watch:
Over the next 60 to 90 days, agribusiness executives, commercial lenders, and feed procurement directors must closely track the formal congressional allotment process and administrative milestones governing the release of the $57.4 million in MPPEP funds. Stakeholders should evaluate how quickly tentative awardees finalize engineering specifications, secure matching private capital, and obtain necessary state environmental permits and federal USDA FSIS inspection approvals. In addition, feed industry participants must monitor commercial construction and cold-storage supply chains across rural corridors, as lead times for specialized stainless-steel processing machinery, refrigerated carcass storage facilities, and wastewater treatment infrastructure will dictate when new slaughter capacity realistically comes online. Facility operators will also face intense competition for skilled meat-cutting labor, making regional workforce training programs a critical operational benchmark for achieving projected commercial throughput heading into 2027.
Looking toward the broader multi-year production cycle, livestock market analysts and commodity risk managers must observe whether expanded processing access triggers a tangible shift in producer breeding decisions, particularly across cow-calf and commercial sow herds. Market participants should scrutinize monthly USDA Cattle on Feed reports and quarterly Hogs and Pigs surveys to determine whether heifer retention rates and breeding herd numbers begin expanding in regions surrounding newly capitalized independent processing facilities. Simultaneously, agribusiness professionals should monitor ongoing federal regulatory initiatives under the Packers and Stockyards Act, evaluating whether enhanced market competition and newly enforced price transparency rules succeed in narrowing the wide margin spread between live animal farm prices and wholesale wholesale meat cutout values. A sustained expansion of independent slaughter capacity will serve as a vital leading indicator for long-term domestic feed grain demand, dictating baseline corn and oilseed meal consumption as herd rebuilding gains momentum across primary livestock production belts.
The Bottom Line
The USDA's $57.4 million investment in 147 independent meat and poultry processing facilities across 40 states delivers a vital structural breakthrough for the American livestock and feed complex, directly confronting the concentrated packing bottleneck that has long compromised producer leverage and inflated feeding expenses. By establishing decentralized regional shackle space, this federal initiative mitigates the risk of costly feedlot backlogs, shields livestock operations from diminishing feed conversion efficiency, and decentralizes commercial feed demand across regional feed mills and grain merchandisers. For commercial feed manufacturers, animal nutritionists, and livestock producers, expanding independent processing infrastructure reinforces supply chain resiliency, fosters transparent market competition, and establishes a durable foundation for long-term herd rebuilding and agricultural profitability.