
The Story:
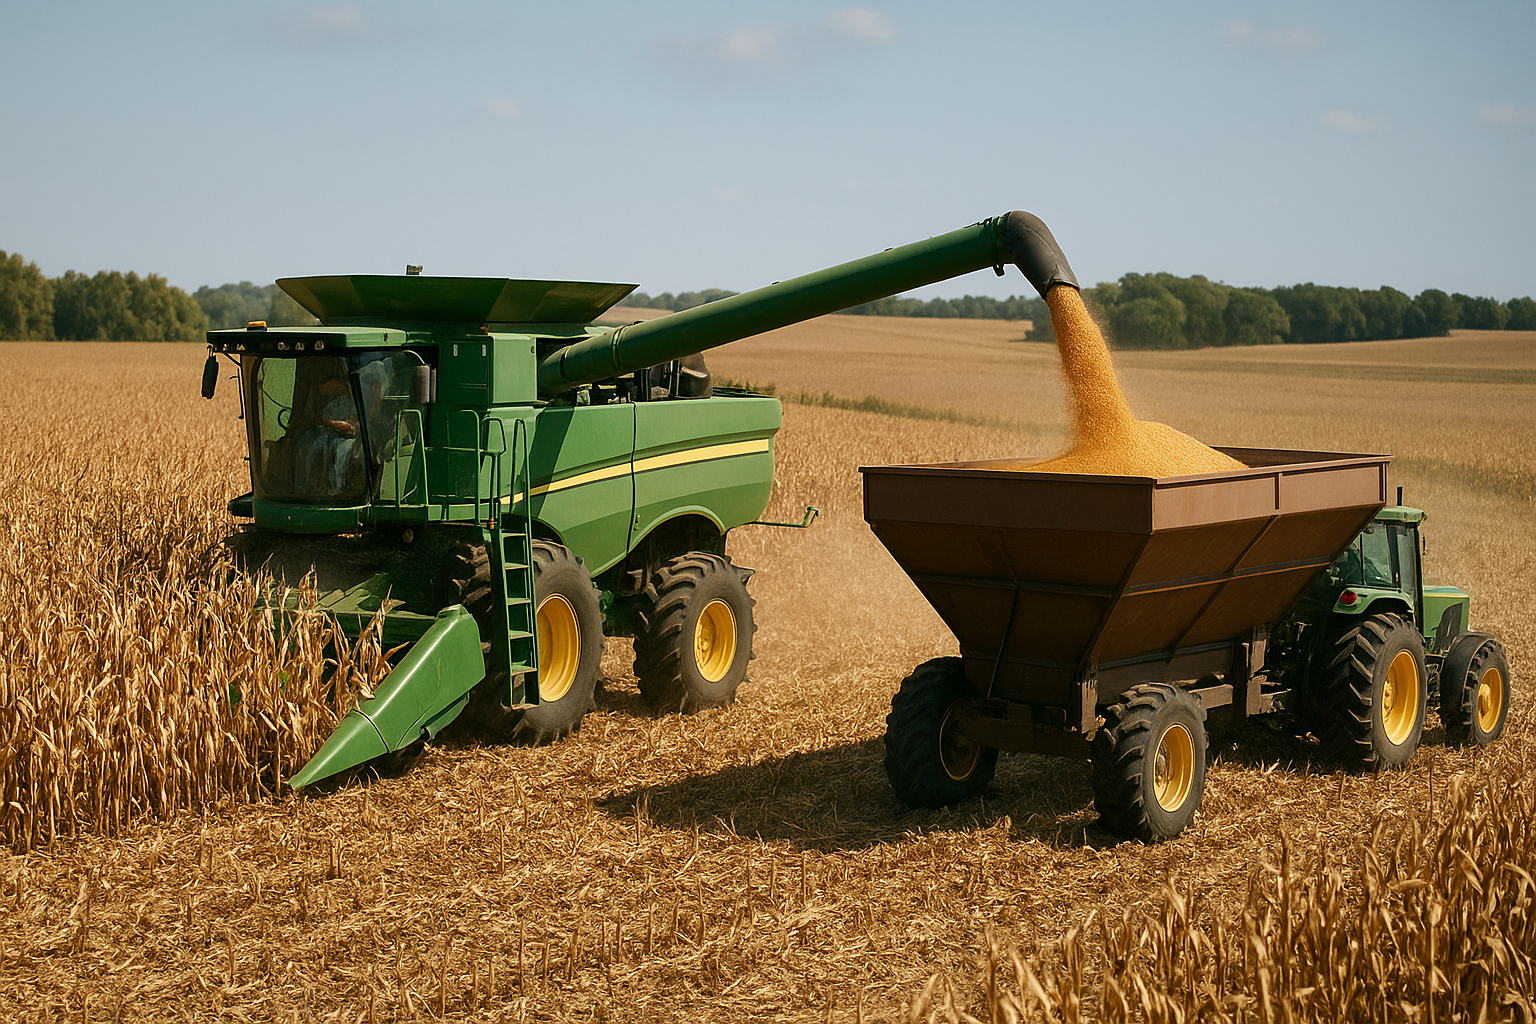
On Friday, October 23, 2026, the Commodity Futures Trading Commission (CFTC) published its weekly Commitments of Traders (COT) report, documenting the most aggressive single-week speculative liquidation across agricultural commodity markets seen during the 2026 calendar year. Institutional managed-money investment funds slashed their net-long positioning in benchmark Chicago Board of Trade (CBOT) corn futures and options by a massive 82,022 contracts during the weekly positioning window ending Tuesday, October 20. The steep retreat reduced overall fund net-long exposure by one-third in a span of just five trading sessions, plummeting from 246,425 contracts down to 164,423 contracts. This rapid institutional drawdown represents the paper liquidation of approximately 410 million bushels of grain, signaling an emphatic and synchronized surrender of speculative weather and production risk premiums by institutional money managers. The aggressive fund selling was triggered by relentless, uninterrupted harvest progress across foundational Corn Belt states—including Illinois, Iowa, Indiana, and Nebraska—where dry, warm mid-October weather enabled commercial combining crews to operate at peak seasonal velocity. With commercial yield monitor telemetry and elevator scale tickets widely confirming the U.S. Department of Agriculture's (USDA) projection of a record-setting national yield of 181.2 bushels per acre and a massive 16.034 billion bushel total crop, speculative trading desks moved swiftly to dismantle long exposure ahead of peak physical harvest delivery.
The surge of speculative fund liquidation exerted immediate, heavy downward pressure across the CBOT futures curve, driving active benchmark December corn futures contracts into a sharp decline that challenged psychological support at $4.60 per bushel and punctured key technical moving averages. This drop in underlying exchange futures directly exacerbated a parallel collapse in interior cash delivery basis across the rural Midwest, where commercial country grain elevators, ethanol grind facilities, and river export terminals found themselves inundated by an avalanche of freshly harvested grain. Commercial elevator operators and grain merchandisers entered the 2026 autumn marketing campaign contending with elevated commercial borrowing interest rates near 8 percent, making the financial carry cost of financing unhedged physical grain inventory in commercial storage tanks the most expensive in more than fifteen years. Unwilling to tie up working capital lines and absorb costly carrying charges on massive incoming piles, commercial elevators aggressively widened spot cash basis bids—posting wide interior delivery discounts ranging from 35 to 55 cents under December futures in heavy production zones—while implementing steep drying and moisture-shrink deductions. The convergence of speculative fund capitulation on the board and heavy physical selling by grain handlers eager to clear space created an intense seasonal supply squeeze, driving flat cash corn prices across interior livestock feeding corridors to their most attractive procurement levels of the entire harvest cycle.
While managed-money funds staged a historic retreat from the feed grains complex, the CFTC data revealed a stark and widening structural divergence across the broader oilseed and feed protein markets. In sharp contrast to the massive liquidation witnessed in corn, institutional funds trimmed their net-long exposure in CBOT soybean meal futures by a minor 3,765 contracts, maintaining an exceptionally robust net-long position of 200,878 contracts. This positioning keeps speculative soybean meal holdings near five-year seasonal record highs for late October. Despite aggressive domestic soybean combining and record-breaking monthly domestic crush grinds reported by the National Oilseed Processors Association (NOPA), speculative fund managers have tenaciously defended meal length, supported by strong baseline domestic feed consumption across expanding commercial poultry and swine operations alongside resilient export sales commitments. This pronounced speculative divergence has pushed the benchmark soybean meal-to-corn price ratio to elevated marks exceeding 2.3 to 1, with December soybean meal hovering near $348 per short ton while corn sinks toward multi-month lows. For commercial feed compounders and livestock nutritionists, this development establishes an acute operational contrast: an abundant, depreciating starch energy supply set against stubbornly priced, tightly held protein co-products across commercial delivery corridors.
Why It Matters:
For commercial animal feed manufacturers, integrated broiler and turkey complexes, table-egg producers, swine integrators, and High Plains commercial cattle feedyards, this massive speculative liquidation in corn futures marks the definitive opening of the 2026/27 seasonal feed procurement window. In commercial livestock and poultry nutrition, yellow dent No. 2 corn serves as the foundational energy baseline, regularly constituting 60 to 75 percent of total physical diet mass in standard finishing and lactation rations. The simultaneous retreat in CBOT futures and widening of interior cash basis has stripped between $15 and $22 per short ton from delivered grain costs compared to late-summer baseline estimates, providing direct and immediate margin relief to feeding enterprises that have battled depressed packer meat cutouts, elevated feeder animal purchase costs, and tight working capital. Commercial cattle feedlots finishing yearling steers on energy-dense steam-flaked corn rations and commercial pork producers across the upper Midwest can now capture meaningful reductions in calculated cost of gain (COG), lowering forward break-even thresholds on finishing groups scheduled for market slaughter through the second quarter of 2027. Agribusiness procurement directors who maintained defensive, short-term coverage postures through September are now actively stepping into the market, locking in physical basis contracts and forward grain deliveries through the first half of 2027 before cold-weather river freezes and post-harvest elevator carry charges inevitably re-inflate regional cash pricing.
Simultaneously, the dramatic pricing wedge opening between collapsing corn values and historically expensive soybean meal requires an immediate, disciplined recalibration of least-cost feed formulation matrices. With the soybean meal-to-corn price ratio stretched well above historical norms, commercial feed mill nutritionists cannot afford to rely on static ration designs. Nutrition desks must aggressively optimize feed additive and synthetic amino acid inclusion parameters to systematically displace high-cost intact vegetable proteins. By elevating dietary inclusion rates of supplemental crystalline L-lysine, L-threonine, DL-methionine, and L-tryptophan, commercial compounders can safely drop crude protein targets by 1.5 to 2.5 percentage points without sacrificing standardized ileal digestible (SID) amino acid balances, animal average daily gain (ADG), or lean meat deposition. Furthermore, feed formulators must leverage secondary co-product streams, utilizing dry-mill distillers dried grains with solubles (DDGS), corn gluten feed, and wheat middlings to capture economical protein and phosphorus units while displacing expensive intact soybean meal. By coupling forward corn basis coverage with precision synthetic amino acid optimization, commercial feed compounders can insulate livestock operations against protein inflation while extracting maximum economic value from the speculative selloff currently sweeping the grain belt.
What to Watch:
Over the next two to four weeks, feed procurement directors, grain merchandisers, and commercial livestock risk managers must closely observe the pace of late-season harvest deliveries and analyze subsequent CFTC weekly positioning releases to verify whether institutional funds extend their corn liquidation into an outright net-short stance. As Midwest combining operations push past the 80 to 90 percent completion mark entering early November, the seasonal peak of physical farm delivery will begin to taper, transitioning commercial grain elevators from emergency receiving mode into structured winter storage management. Market participants must monitor whether managed-money funds continue aggressive technical short-selling or whether speculative desks determine that prices near $4.60 per bushel represent an oversold valuation floor, potentially setting the stage for an abrupt short-covering rally if commercial export inspections or domestic ethanol grind demand surprise to the upside. In addition, commercial buyers should scrutinize the forthcoming November USDA Crop Production and World Agricultural Supply and Demand Estimates (WASDE) reports, verifying whether federal analysts affirm the record 181.2 bushel yield baseline or introduce revisions following objective yield field data integration.
Concurrently, commercial feed compounders and livestock production executives must track regional cash basis spreads, processing crush dynamics, and winter logistics corridors throughout the Mississippi River basin. Procurement teams should monitor daily barge freight rate tariffs on the Upper Mississippi and Illinois waterways, assessing whether recurring low-water navigational restrictions slow export loadings at the Gulf of Mexico, trapping additional uncommitted grain within interior domestic feeding territories. Nutrition directors should also track processor soybean meal basis sheets as crush plants run at full capacity to meet seasonal oil demand, determining whether regional meal inventories begin to accumulate and soften spot basis levels toward year-end. Finally, feedyard operators and grain buyers should watch commercial elevator merchandising strategies through December, evaluating whether high commercial borrowing interest rates force country elevators to liquidate outdoor emergency grain piles at steep discounts, or whether well-capitalized producers with ample on-farm grain bin capacity succeed in locking away sufficient bushels to ignite a fiercely competitive post-harvest battle for local cash grain basis.
The Bottom Line
The CFTC's revelation that institutional managed-money funds slashed their net-long corn position by 82,002 contracts in a single week marks a transformative sentiment turning point across North American agricultural markets, converting peak harvest supply pressure into a prime forward buying opportunity for the animal feed sector. With record corn yields inundating commercial elevators and pressing December futures toward $4.60 per bushel, commercial feed manufacturers, swine integrators, poultry complexes, and cattle feedlots possess a powerful operational window to secure favorable interior cash basis and lock in physical grain energy requirements well into 2027. By pairing strategic forward grain coverage with precision synthetic amino acid supplementation and co-product balancing against stubbornly expensive soybean meal, livestock producers and feed compounders can defend operating margins, optimize herd feed conversion efficiency, and establish durable economic resilience across the evolving commodity landscape.