
The Story:
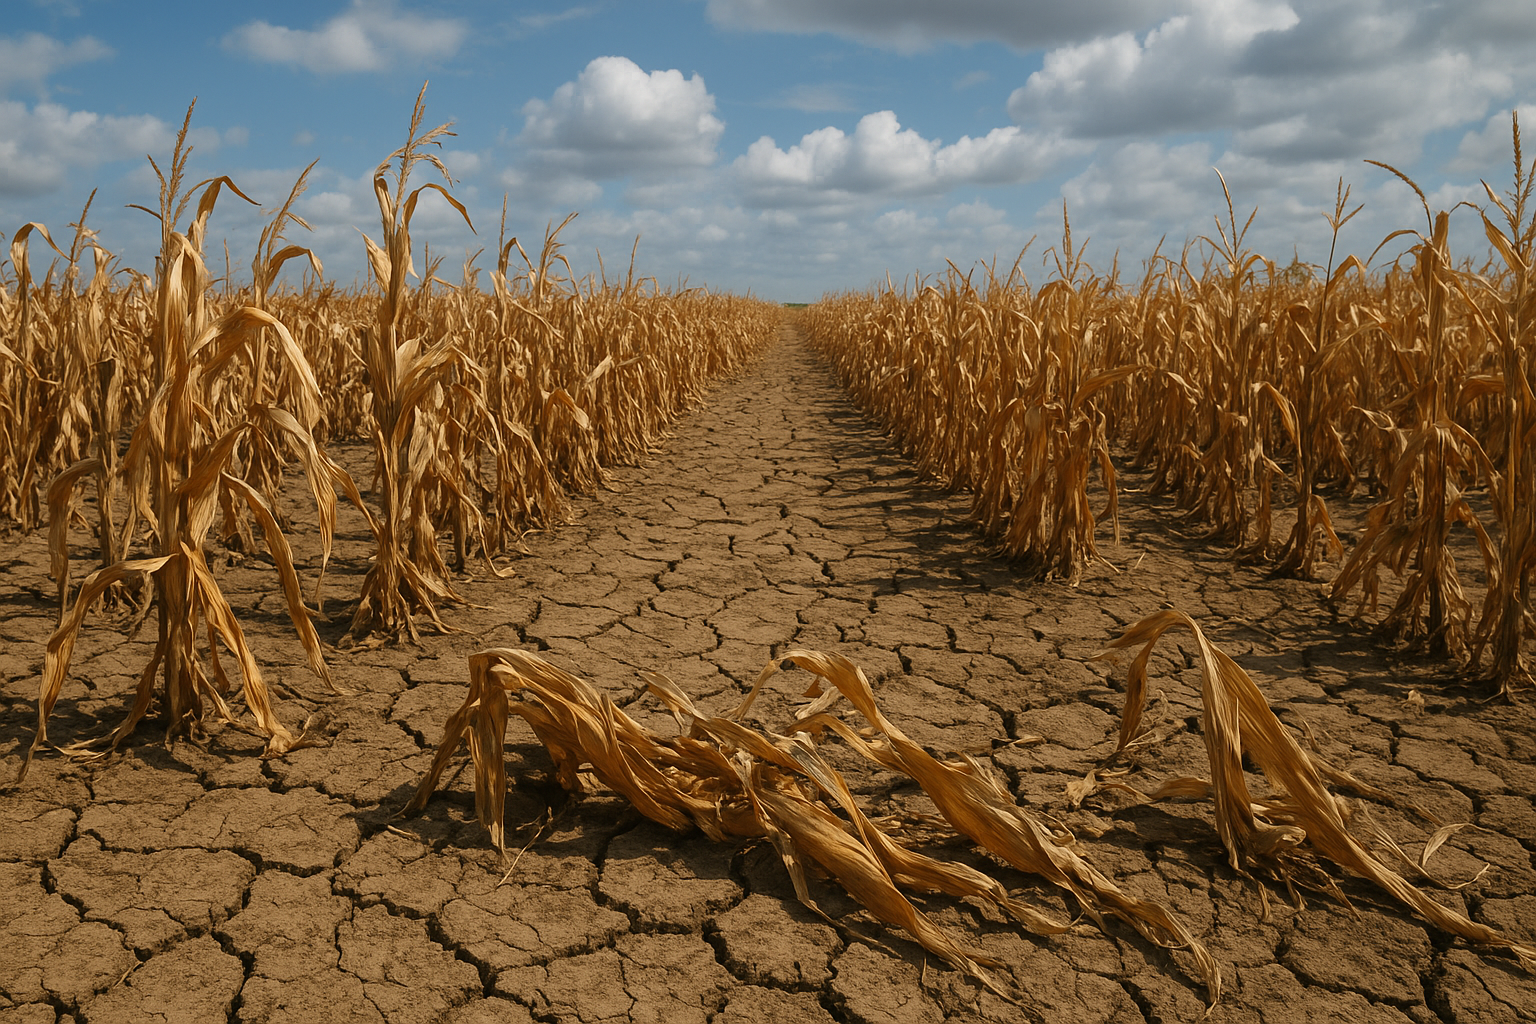
On Thursday morning, October 29, 2026, the National Drought Mitigation Center (NDMC), the U.S. Department of Agriculture (USDA), and the National Oceanic and Atmospheric Administration (NOAA) officially released the weekly U.S. Drought Monitor assessment for conditions valid through October 27, 2026, confirming a renewed expansion of drought conditions across key agricultural production basins. Nationally, moderate-to-exceptional drought categories (D1 through D4) widened to encompass approximately 28 percent of total U.S. soybean production acres and 21 percent of domestic corn production acres, with each registering a one percentage point increase compared to the prior reporting week. While broad moisture patterns across the western Corn Belt and Northern Plains maintained localized stability following scattered precipitation, severe-to-extreme drought (categories D2 to D3) deepened and expanded across the Lower Mississippi River Valley and interior Delta regions, intensifying long-term hydrological stress across core logistical corridors. Over the preceding four months, critical producing and shipping zones across Arkansas, Louisiana, Mississippi, and western Tennessee have accumulated severe precipitation deficits ranging from 8 to 16 inches below historical averages, leaving cumulative seasonal rainfall across the lower basin at less than half of normal levels.
The acute concentration of drought conditions throughout the Lower Mississippi River basin has triggered severe operational strain along the primary inland marine artery responsible for moving Midwest feed grains and oilseeds to deepwater export elevators along the U.S. Gulf Coast. River gauges along the lower stem of the Mississippi River, most prominently at the key monitoring station in Memphis, Tennessee, fell to near and below negative foot gauge stages heading into late October, exposing extensive sandbars and significantly narrowing navigable river channels. In response to deteriorating channel depth, commercial inland barge operators and towing lines have implemented mandatory navigational restrictions, slashing allowable barge operating drafts from standard 11- to 12-foot loading depths down to 9 feet or lower, while enforcing strict reductions on maximum tow configurations. Industry logistics models confirm that each one-foot reduction in operating draft removes between 150 and 200 metric tons of cargo carrying capacity per individual barge. This mandatory draft restriction curtails the aggregate payload efficiency of standard 15- to 30-barge flotillas by 15 to 25 percent, stranding substantial tonnage at interior river loading elevators and sharply slowing turnaround times.
This hydrological bottleneck arrives at the most critical juncture of the agricultural marketing year, directly colliding with peak autumn harvest velocity and massive international export commitments confirmed in this morning's USDA Foreign Agricultural Service weekly Export Sales report. With aggregate commercial export sales exceeding 4.7 million metric tons—propelled by 2.58 million metric tons of whole soybeans and 1.30 million metric tons of feed corn—the logistical demand for prompt vessel loadings at New Orleans and Baton Rouge export terminals is cresting just as barge shipping capacity contracts. The compounding friction of lighter-loaded barges, diminished tow sizes, and slower transit speeds has triggered a sharp escalation in spot river freight rates, forcing interior river elevators to widen cash basis discounts to country producers to absorb surging waterborne freight premiums. While unseasonably dry October weather has allowed commercial harvesting to proceed without interruption—advancing nationwide corn harvest past 60 percent and soybean harvest beyond 64 percent—the inability to fluidly evacuate bulk volume downstream is backing up physical grain supplies and creating acute regional basis dislocations across the interior supply chain.
Why It Matters:
For commercial animal feed manufacturers, livestock integrators, and grain merchandisers, the collision of low-water Mississippi River restrictions and robust offshore export commitments fundamentally alters interior grain movement, origination economics, and spot basis relationships. River terminal elevators situated along the Illinois, Ohio, and middle Mississippi rivers that normally purchase heavy volumes of newly harvested grain to assemble Gulf-bound export tows are being penalised by soaring barge freight and reduced vessel turnarounds. To protect operating margins and prevent elevator silos from reaching capacity limits, these river facilities are widening cash basis discounts against Chicago Board of Trade futures. While this dynamics softens local spot grain prices immediately adjacent to river terminals, it intensifies physical competition across interior domestic livestock feed corridors. Commercial feed compounders and integrated broiler, layer, and swine operations across the Eastern and Western Corn Belt cannot rely on cheap harvest delivery; instead, they must actively compete against rail shuttle facilities and domestic processing plants that are capturing grain originally earmarked for river export, driving up delivered ingredient costs in interior feeding complexes.
At animal nutrition desks and feed procurement departments, river logistics disruptions are driving significant shifts in ingredient formulation and protein meal availability. Domestic soybean processing facilities, running near maximum capacity to satisfy both export commitments and domestic ration demands, rely on dependable outward transport to prevent physical inventory congestion. When barge movements south are restricted, crushers are forced to push larger volumes of high-protein soybean meal into domestic rail and truck markets, creating localized price soft spots in processing hubs while driving delivered meal prices higher in deficit feeding regions like the Southeast. Simultaneously, commercial livestock producers navigating tight hog margins and elevated feeder cattle prices are scrutinizing daily ration economics. With benchmark futures markets suppressed by the massive crop size, the dominant cost variable for feed mill managers is localized freight and basis. Nutritionists are actively optimizing rations by expanding the inclusion of corn co-products—leveraging record domestic fuel ethanol production of 1.118 million barrels per day to incorporate distillers dried grains with solubles (DDGS) at 10 to 15 percent—while strategically balancing crystalline amino acids, particularly L-lysine HCl, DL-methionine, and L-threonine, to displace expensive intact protein and insulate commercial livestock budgets from transport volatility.
What to Watch:
Over the next two to four weeks, feed procurement directors, grain merchandisers, and livestock risk managers must closely track Mississippi River stage projections and National Weather Service Extended Streamflow Forecasts, focusing particularly on critical navigational choke points at Cairo, Illinois and Memphis, Tennessee. The prolonged absence of substantial soaking precipitation across the Ohio and upper Mississippi river valleys will keep water levels depressed, requiring the U.S. Army Corps of Engineers to maintain continuous 24-hour emergency dredging operations across shallow river crossings to prevent catastrophic channel closures and tow groundings. Merchandising desks must closely monitor the weekly USDA Agricultural Marketing Service Grain Transportation Report for spot barge freight rate indices, while auditing secondary freight spreads across Class I railroad networks including BNSF Railway, Union Pacific, CSX, and Norfolk Southern. Any sustained spike in river barge costs will accelerate the diversion of bulk corn and soybean meal onto domestic unit trains, creating localized railcar shortages, higher freight tariffs, and extended rail dwell times into southeastern poultry and swine regions.
Concurrently, feed mill purchasing managers and livestock production executives must watch interior elevator commercial storage dynamics as autumn harvest operations conclude over the first half of November. If low-water river restrictions persist and downstream grain evacuation remains constrained, interior commercial elevators may quickly exhaust physical storage capacity, forcing grain handlers to impose steep commercial drying charges, widen delayed-pricing discounts, or restrict incoming truck deliveries. Such localized gluts offer opportunistic buying windows for commercial feed manufacturers equipped with substantial on-site grain storage to lock in highly advantageous physical corn and co-product basis. Procurement teams should capitalize on any harvest-related interior basis weakness over the coming days to establish forward physical coverage on corn, high-protein soybean meal, and essential amino acids through the first quarter of 2027, safeguarding feeding programs against the inevitable logistics friction and winter weather disruptions that follow late harvest.
The Bottom Line
The October 29 U.S. Drought Monitor confirmation that drought has expanded across 28 percent of U.S. soybean acres and 21 percent of corn acres—compounded by severe rainfall deficits driving the lower Mississippi River to negative gauge stages and triggering mandatory barge draft and tow restrictions—creates an acute logistics chokepoint at the peak of autumn harvest and offshore export demand. For animal feed manufacturers, commercial livestock integrators, and grain merchandisers, restricted river capacity widens river cash basis discounts, redirects interior grain flows, and elevates the necessity of proactive logistics and basis risk management. Operations that actively monitor river stages and rail freight differentials, capitalize on localized interior grain discounts, and dynamically optimize feed formulations using DDGS and synthetic amino acids will successfully protect animal performance and shield their operating margins from mounting transportation friction heading into the winter feeding season.